
Filing VAT returns in the UAE needs accurate financial records, proper invoice checks, and timely submissions through the EmaraTax portal. So, a business should reconcile input and output VAT, follow filing deadlines, and review its returns to avoid penalties and errors.
Key Takeaways:
- VAT returns are generally due within 28 days after each tax period ends.
- Checking input and output VAT records may help prevent mistakes during the filing procedures.
- Businesses must keep their VAT records for the required period, which is usually at least five years.
- So, if you review returns before submission, it will help identify errors and reduce compliance risks.
To file Value Added Tax (VAT) returns on time is an important responsibility for businesses registered in the UAE. The Federal Tax Authority (FTA) Needs businesses to keep accurate financial records and submit their returns through the EmaraTax portal.
If any business misses this deadline or enters incorrect information. it can lead to penalties. Therefore, keep your accounts updated and review tax calculations before submission. This can help you avoid common mistakes and stay compliant with the UAE tax rules.
Understanding Your VAT Filing Deadlines and Schedules
Every VAT-registered business in the UAE must follow a filing schedule that is set by the FTA. So, depending on the business and its circumstances, returns may be due every month or every three months.
If you know your assigned tax period, it can help you plan your accounting work and avoid missing important deadlines. It will also be important to understand these schedules from the start of your UAE VAT return filing process.
Standard Tax Periods and Statutory Deadlines
The FTA usually assigns VAT tax periods on a quarterly or a monthly basis. Many small and medium-sized businesses can follow quarterly filing schedules. Alternatively, some businesses are required to file every month.
Businesses need to submit their VAT returns and pay any VAT due within 28 days after the relevant tax period ends.
Under the VAT penalty rules effective from 14 April 2026, the penalty for submitting a late return can be AED 1,000 for the first offence. It will become AED 2,000 for a repeat offence within 24 months.
Thus, keep track of your filing dates. It can help you avoid these charges. It is also a good idea to set reminders well before each deadline.
Preparing Portal Data Ahead of Statutory Cutoffs
If you wait until the last day to prepare your VAT return, it can lead to mistakes. If you miss invoices, provide incorrect figures, or face any problems accessing the EmaraTax portal, it can delay your submission.
Begin preparing your records early. Check your sales, purchases, input VAT, and output VAT. You need to do this before you enter the figures into the portal. You might also want to review transactions under standard-rated, zero-rated, and exempt categories.
These details can be prepared in advance. It may give your accounting team enough time to find and correct errors before you submit the return. This can make the overall UAE VAT return filing process easier to manage.
UAE Periodic VAT Return Filing Workflow
A simple filing process can help businesses stay organized and avoid common reporting mistakes.
- Collect Sales and Purchase Records: Gather the invoices, receipts, and other supporting documents.
- Verify Tax Details: Check supplier details, customer invoices, and Tax Registration Numbers (TRNs).
- Reconcile Input and Output VAT: Match the figures in your accounting records and try to identify any differences.
- Complete Form 201: Enter the verified figures into the VAT return section of the EmaraTax portal.
- Submit and Pay: Review the return and submit it before the deadline. So, pay any VAT due.
Essential Guidelines for Complete Tax Return Preparation
Accurate VAT returns depend on good accounting records. If your sales and purchase ledgers are up to date, preparing the return can become much easier.
Before starting the filing process, you might need to check that your inboxes, expense records, and tax calculations are complete. The following table can highlight some key VAT requirements and practical steps that businesses can follow.
| Compliance Parameter | General Requirement | Recommended Practice |
| Standard VAT Rate | 5% on standard-rated supplies | Check tax rates and invoice details before filing |
| Filing Deadline | Within 28 days after the tax period ends | Prepare the return at least seven days before the deadline |
| Record Retention | Generally five years, with 15 years for certain real estate records | Keep digital copies of invoices and supporting documents |
| Late Filing Penalty | AED 1,000 for the first offence; AED 2,000 for a repeat offence within 24 months | Set reminders for every filing deadline |
Table: Important UAE VAT filing requirements and recommended accounting practices
Managing Initial Setup Through VAT Online Registration in the UAE
Before a business can start filing VAT returns, it must complete the required registration with the FTA. The process of VAT online registration in the UAE process involves providing business details and supporting documents through the EmaraTax portal.
You will generally need information such as your trade licence, business activities, contact details, and financial information to complete the application.
It is important to enter these details correctly. Errors in your business information or registration details can create problems when preparing future VAT returns.
Businesses should also check whether they meet the mandatory or voluntary VAT registration requirements. The mandatory registration threshold is AED 375,000 in taxable supplies and imports over the relevant 12-month period. The voluntary registration threshold is AED 187,500.
Completing registration correctly from the beginning makes it easier to manage future tax filings.
Reconciling Sales and Purchase Ledgers for UAE VAT Return Filing
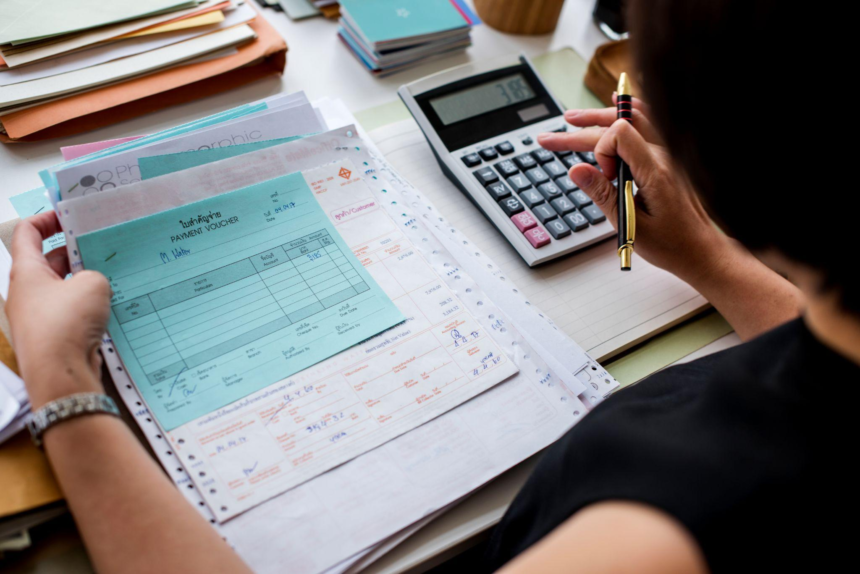
Accurate UAE VAT return filing will start with checking your sales and purchase records. Your output VAT figures should match the tax collected on your sales, while your input VAT figures should be supported by eligible business purchases.
For example, if your sales ledger shows a different amount from your issued tax invoices, you should find the reason before submitting the return.
You should also check whether your purchase invoices meet the FTA’s requirements for input VAT recovery. Keeping supplier details, invoice numbers, and tax amounts organised makes this process easier.
Regular reconciliation helps businesses identify missing invoices, incorrect tax entries, and other issues before they become filing problems.
Conclusion
Filing VAT returns in the UAE becomes easier when businesses maintain accurate records, check their invoices, and follow the FTA’s deadlines. Regularly reviewing sales and purchase ledgers also helps identify errors before submitting a return.
Ready to Make Your UAE VAT Filing Easier?
Managing VAT deadlines and financial records can take time, especially when your business handles multiple transactions. Get professional support to review your accounts, check your VAT calculations, and manage your filing requirements. Speak with an experienced UAE tax specialist to make your VAT compliance process simpler and more organized.